
Tax planning for sole traders, landlords and limited companies
We plan your tax before the year end: how you take money out, which reliefs and allowances you can claim, and what to set aside each month, so you know the bill before it is due.
Call or WhatsApp 07476 989568

Tax support for business owners
In the company
Corporate tax planning
Company tax planning, profit extraction, timing of income and expenditure, group structures, and tax-efficient decisions around growth and investment.
Tax reliefs and specialist planning
Reliefs and allowances, innovation-related claims, business investment planning and capital expenditure planning.
Paying yourself and your team
Personal tax for business owners
Salary and dividends, personal tax planning, director tax efficiency, income extraction, benefits and allowances, and planning around major decisions.
Employment taxes
PAYE, benefits and expenses, director remuneration, staff-related tax issues, payroll-linked queries and employment status.
Shareholder, growth and reward planning
Tax-efficient ways to reward and incentivise your people, and to plan for the future of the business.
Selling or handing on
Exit planning
Planning for a future sale, succession planning, and extracting value tax-efficiently before a transaction.
Estate and succession planning
Inheritance tax planning, estate planning, succession, family wealth and longer-term tax efficiency.
When to start planning
Once a company is sold, a property transferred, a dividend paid or a year ended, all that is left is reporting what happened.
Company year end
Profit extraction and capital spend: three to four months before the year end.
Selling the business
Business Asset Disposal Relief conditions: at least a full tax year before the sale.
Buying property
Before the property is bought. Moving it later triggers Capital Gains Tax and Stamp Duty.
HMRC support and tax compliance
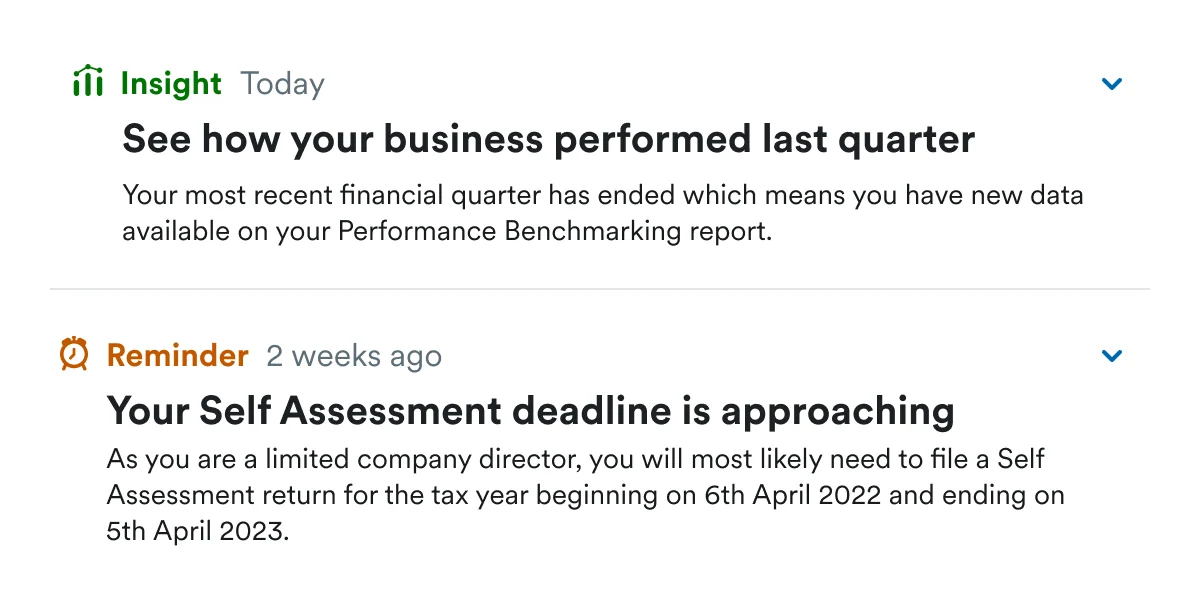
Tax returns and reporting, help with HMRC queries, support if something has gone wrong, and fewer avoidable mistakes.
If HMRC opens an enquiry
We take over the correspondence and you stop dealing with HMRC directly. We read the opening letter carefully, because what is being asked for is usually narrower than it reads, agree what to provide and what to challenge, request extensions where a statutory deadline is tight, and keep a written record of everything sent. Most enquiries are aspect enquiries into a single figure rather than a full review of the books and records, and many close without a change. Whether enquiry work sits inside your fee or is quoted separately depends on your engagement letter, so ask before you need it.
Talk to us about HMRCHow much tax to set aside
Sole trader
Reserve for Income Tax and Class 4 National Insurance on profit, plus VAT if you are registered.
Allow for payments on account. In the first full year, January brings the previous year’s tax and half of the next year’s on the same day.
Limited company
Reserve Corporation Tax as profits are earned.
It is payable nine months and a day after the company’s year end.
Move the reserve to a separate account the day the money lands.
Common tax questions
What does tax planning cost, and is it inside my package?
It sits outside a compliance fee and is quoted separately, either as a fixed fee for a piece of work or built into an ongoing advisory arrangement. You get the figure before anything starts. Preparing and filing a return is the same job each year. Planning a profit extraction strategy, an exit or a group restructure is priced for the work it involves.
What is the difference between tax planning and tax avoidance?
Planning uses reliefs and structures in the way Parliament intended: pension contributions, capital allowances, the timing of income and expenditure, choosing the right business structure, and using both spouses’ allowances. Avoidance schemes use arrangements that technically comply while producing an outcome nobody legislated for, and HMRC attacks them through the general anti-abuse rule, DOTAS disclosure, follower notices and accelerated payment notices. We do tax planning. If someone offers a scheme promising to turn income into a tax-free loan or a capital gain, expect HMRC to challenge it and expect to pay the bill yourself.
Where do tax savings usually come from?
The salary and dividend split, pension contributions, capital allowances timed properly, using a spouse’s allowances and bands, and the choice of business structure. Those are worth real money over years. In plenty of cases the current position is already reasonable and there is nothing material to change.
Do you do R&D claims and other reliefs?
We check whether you have a claim. R&D relief requires an advance in science or technology with genuine technical uncertainty. A new website, a bespoke customer system or a product that is simply new to your market does not qualify. HMRC has tightened enforcement after widespread abuse by claims firms, with mandatory pre-notification, detailed additional information forms and a high rate of enquiry. A genuine claim is valuable and worth doing properly with contemporaneous records. For a marginal claim, the enquiry risk usually outweighs the benefit.
Tax planning with a financial adviser
We handle allowances, timing and whose name an asset is in. Recommendations on pensions, investments and other financial products come from Buzz Financial Services, a separate firm authorised to give them.
Buzz Financial Services is a trading style of Equity & General Financial Services Limited, which is authorised and regulated by the Financial Conduct Authority (No. 474163).
Talk to Buzz about your tax
Start with a conversation
We talk through your business, your current setup and where you want to go.
Agree what matters
We identify the risks, opportunities and areas that need attention.
Build the plan
How you take money out, which reliefs and allowances you claim, and what to set aside each month.
Keep it current
Ongoing support as your business and life change.
Call or WhatsApp 07476 989568 or email hello@buzzaccounting.co.uk
Accreditations and partnerships








